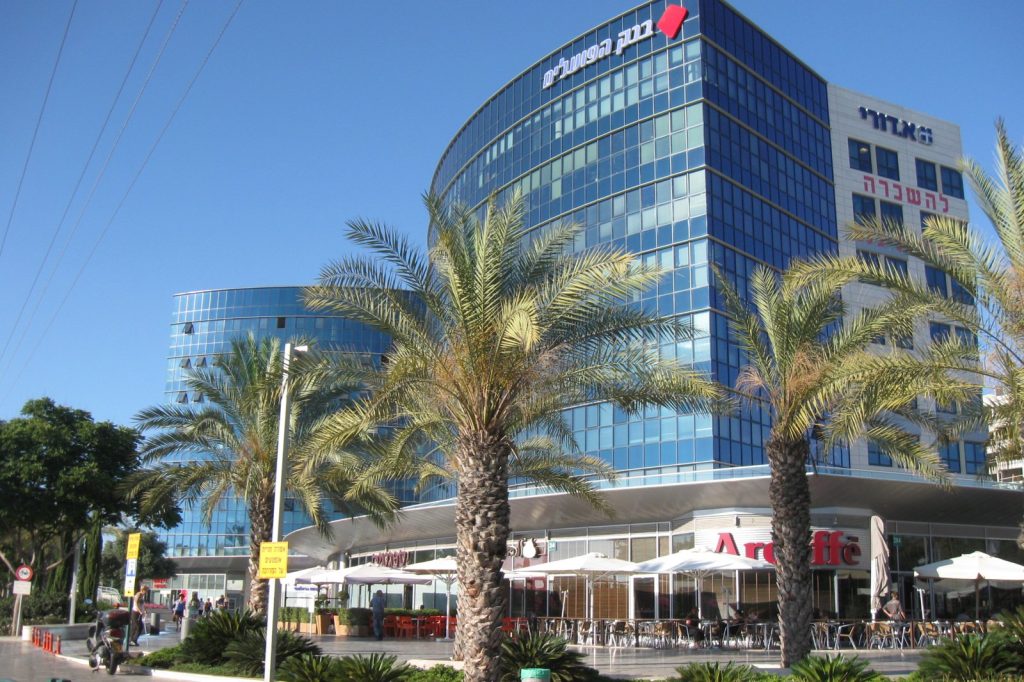
A deferred prosecution agreement (DPA) filed in 2020 between Bank Hapoalim and U.S. authorities has entered the public record, revealing that the Israeli bank paid $30 million to settle allegations it had facilitated bribe payments linked to the FIFA corruption scandal. The agreement, however, does not constitute a criminal conviction; rather, it reflects a negotiated settlement that allowed prosecutors to defer filing charges while the bank complied with a set of remedial conditions.
Under the terms of the DPA, Bank Hapoalim agreed to cooperate fully with regulators, strengthen its internal controls and address the compliance shortcomings that allegedly enabled illicit funds to move through its systems. In exchange, prosecutors agreed not to pursue criminal charges, provided the bank met these obligations. The settlement therefore signals that authorities found sufficient evidence to bring a case, but also that the bank’s cooperation was deemed adequate to avoid a trial.
Founded in 1921 as “The Workers’ Bank,” Bank Hapoalim has long been a cornerstone of Israel’s financial landscape. With more than 250 branches both domestically and abroad, the institution is listed on the Tel Aviv Stock Exchange under the ticker POLI and is a component of the Tel Aviv 35 Index, which tracks the nation’s largest publicly traded companies. Such a high‑profile status brings heightened expectations for corporate governance and compliance.
The FIFA episode exposed a breach in those expectations. While the exact details of the compliance failures remain unclear, regulators concluded that the bank’s internal safeguards allowed bribe‑related transactions to be processed. The DPA does not require the bank to admit guilt, a standard feature of such agreements, but it does acknowledge that misconduct occurred under the bank’s watch.
Bank Hapoalim serves a diverse client base, ranging from retail depositors to corporate and institutional customers. The alleged bribe payments flowed through the same channels used by millions of ordinary account holders, though those customers were not responsible for the compliance lapses. The settlement’s $30 million payment, while sizable, is not financially crippling for an institution of this scale; the more significant impact lies in reputational damage, heightened regulatory oversight, and the imperative to rebuild trust.
The DPA’s closure of the legal case does not settle broader questions about systemic risk within Israel’s banking sector. As one of the country’s largest banks, Hapoalim’s compliance shortcomings set a precedent that could influence regulatory expectations for other domestic lenders. If a bank with extensive branch coverage and a spot on the Tel Aviv 35 Index can become entangled in a global corruption scandal, the potential exposure for other institutions is considerable.
In summary, the 2020 deferred prosecution agreement underscores three key points: first, Bank Hapoalim avoided a criminal conviction by meeting the conditions set by U.S. prosecutors; second, the $30 million settlement reflects both the seriousness of the alleged violations and the bank’s capacity to pay; and third, the case highlights the ongoing need for robust anti‑money‑laundering controls in major financial institutions, especially those with a high public profile.