Founded in 1911 by the Australian government, the Commonwealth Bank of Australia has evolved into one of the nation’s largest financial institutions. Fully privatized in 1996, it now stands as a pillar of the “big four” banks, alongside National Australia Bank, ANZ, and Westpac.
Its operations span retail, business, and institutional banking, as well as funds management, superannuation, insurance, investment, and broking services. The group includes well-known brands such as Bankwest, Colonial First State Investments, ASB Bank in New Zealand, CommSec, and CommInsure. The bank listed on the Australian Stock Exchange on September 12, 1991.
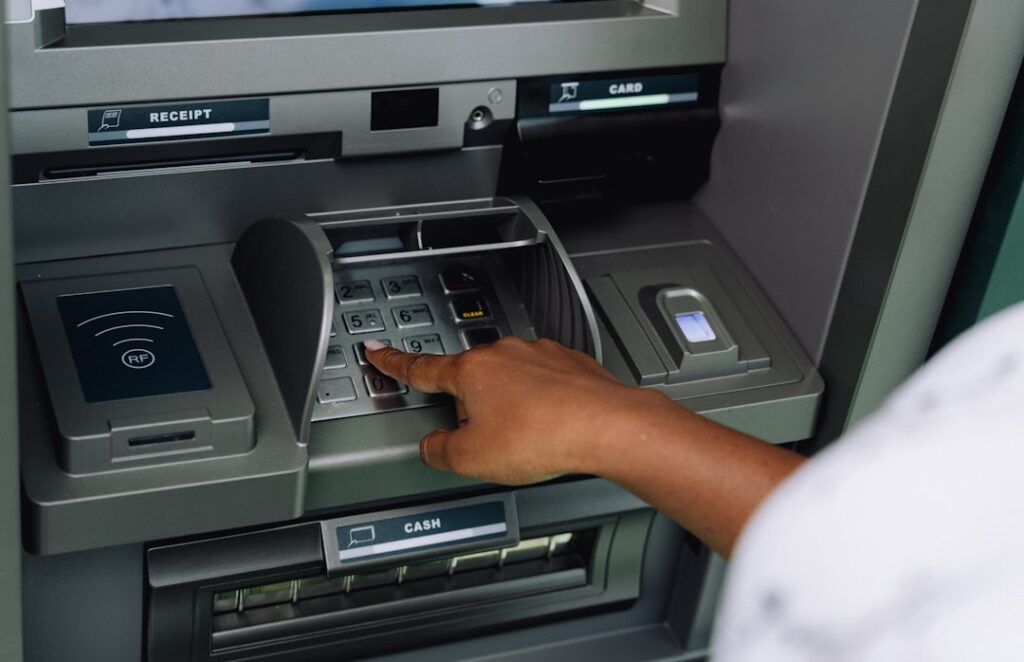
Today, the bank faces allegations of 53,000 breaches of anti-money laundering rules. These alleged breaches were reportedly facilitated through its smart-deposit ATMs.
These machines allow customers to deposit cash and cheques without an envelope, offering speed and convenience. However, the same efficiency that appeals to legitimate customers also attracts those seeking to move money quickly. According to reports, the bank’s machines became a channel for these alleged violations.
The exact mechanism—how the ATMs were used to bypass checks—is central to the regulatory case. The bank’s size and history lend weight to the allegations.
A 106-year-old institution, once a government creation and now a private giant, is accused of failing to police its own machines. This is not a new challenge; banks have long struggled to balance customer convenience with compliance. Automated systems handle deposits faster than human tellers, but speed can outrun oversight.
The Commonwealth Bank’s smart-deposit ATMs processed thousands of transactions, with the allegation that 53,000 of them broke the rules. That number suggests a pattern, not a glitch.
The report was published on August 7, 2017. The bank has been listed on the Australian Stock Exchange since 1991 and fully privatized since 1996. For over two decades, it operated as a private company, subject to the same anti-money laundering laws as every other financial institution. The allegations point to a failure in that system.
The bank’s own history—its founding by the government, its long public service role, and its later privatization—makes the case more striking. A bank built by the state is now accused of letting its ATMs become tools for potential money laundering.
The consequences are significant. The Commonwealth Bank is one of the largest Australian listed companies, with widely held stock and millions of users. If the allegations hold, the bank faces not only regulatory penalties but also a loss of trust—a difficult asset to rebuild.
Its brands, including Bankwest, Colonial First State, CommSec, and CommInsure, all rely on that trust. The smart-deposit ATMs were meant to be a convenience, not a vulnerability.
Regulators are watching. The Australian Transaction Reports and Analysis Centre, known as AUSTRAC, is the agency responsible for monitoring compliance. The 53,000 alleged breaches represent a significant enforcement case.
The bank’s response will be scrutinized. Its history offers no shelter.
A bank founded by the government, privatized, and now one of the big four cannot claim ignorance of the rules. The machines did what they were programmed to do. The question is whether the bank programmed them to check.